Camas Advice · Long-Term Care Planning
You Planned for the Consequences of Dying Too Soon. Have You Planned for the Consequences of Living Longer Than Expected?
A complimentary, no-obligation consultation to show you exactly what long-term care will cost, what your options are, and how to protect the people who matter most.
of Americans turning 65 will need long-term care
median annual cost of a private nursing home room
what Medicare covers for extended custodial care
Sources: U.S. Dept. of Health & Human Services (ACL); 2025 CareScout Cost of Care Survey; Medicare.gov
Nationwide
Advanced Planning
Independent
ACCESS TO ALL CARRIERS
Complimentary
No-Obligation Consultation
You've Built a Beautiful Life. Long-Term Care Can Dismantle It in Months.
You've done the right things. You've saved. You've invested. You've spent years with your CPA, your attorney, your financial advisor — coordinating an estate plan, a tax strategy, a retirement that reflects decades of discipline.
And yet there's a conversation you keep pushing to next quarter, next year, someday.
What happens if you — or your spouse — can no longer live independently?
It doesn't have to be a dramatic diagnosis. It can be a gradual decline — a hip that doesn't heal right, a mind that starts to slip. The need for someone to help with bathing, dressing, and eating. The six basic activities of daily living that most of us take for granted until we can't do them alone.
You Already Understand This Logic. You Just Haven't Applied It Here Yet.
Think about why you bought life insurance. You didn't buy it because you thought you were going to die during your working years. Statistically, you knew that was unlikely. You bought it because you understood that if you were wrong — if the unlikely did happen — the consequences to your family would be catastrophic.
Long-term care planning follows the exact same logic.
LIFE INSURANCE
You didn't think you'd die young. But you knew the consequences would be devastating if you did. So you planned — not because of the risk, but because of what was at stake.
Your family was protected.
Long-Term Care
You may not think you'll need extended care. But 70% of people who reach 65 do. Without a plan, your income, your assets, and your family's well-being are all on the table.
This is the plan you haven't made yet.
The risk may feel low. But what are the consequences of being wrong? Those are the same ones that made you pick up the phone for life insurance years ago. The only difference is this time, you're still here to see what happens to the people you love.
The "Default Plan" Is No Plan at All.
Everyone has a plan for long-term care. The question is whether it's one you chose — or one that chose you.
Without a deliberate plan, you get what we call the Default Plan. It means your family is in crisis mode. It means every dollar you have — your income, your retirement accounts, the equity in your home — is on the table. And it means the people closest to you are the ones absorbing the impact.
Your spouse becomes your caregiver. Not because they're trained for it — because there's no one else. The feeding, the bathing, the transferring. It takes a physical toll first. Then an emotional one. The healthy caregiver becomes unhealthy. And now you have two people who need help.
Your adult children step in. Usually it's one — the oldest daughter, the one who lives closest. She cuts her hours at work. Then she quits. She reorganizes her life around your care while her siblings offer "opinions" and "suggestions" from a distance. The resentment builds. The relationships fracture. And that damage can outlast the person who needed care.
Your finances start to erode — fast. Care costs come out of income first. When income isn't enough, you invade savings. Liquidating retirement accounts triggers ordinary income tax — potentially 30 to 50 cents on every dollar. Selling investments in a down market compounds the damage. And the obligations that don't stop — your spouse's living expenses, the mortgage, commitments to grandchildren — still need to be paid.
One in five people who need care will need it for longer than five years. At $129,000 a year for a private nursing home room — before taxes, before inflation — you can see how quickly a lifetime of wealth can disappear.
will need care for
longer than 5 years
median annual cost of
in-home care (44 hrs/week)
average length of care
needed by women
Sources: U.S. Dept. of Health & Human Services (ACL); 2025 CareScout Cost of Care Survey; Medicare.gov
There's a Way to Face This with Confidence Instead of Fear.
We built this consultation for people who are ready to replace uncertainty with a clear picture — and a real plan.
Camas Advice · Long-Term Care PLANNING
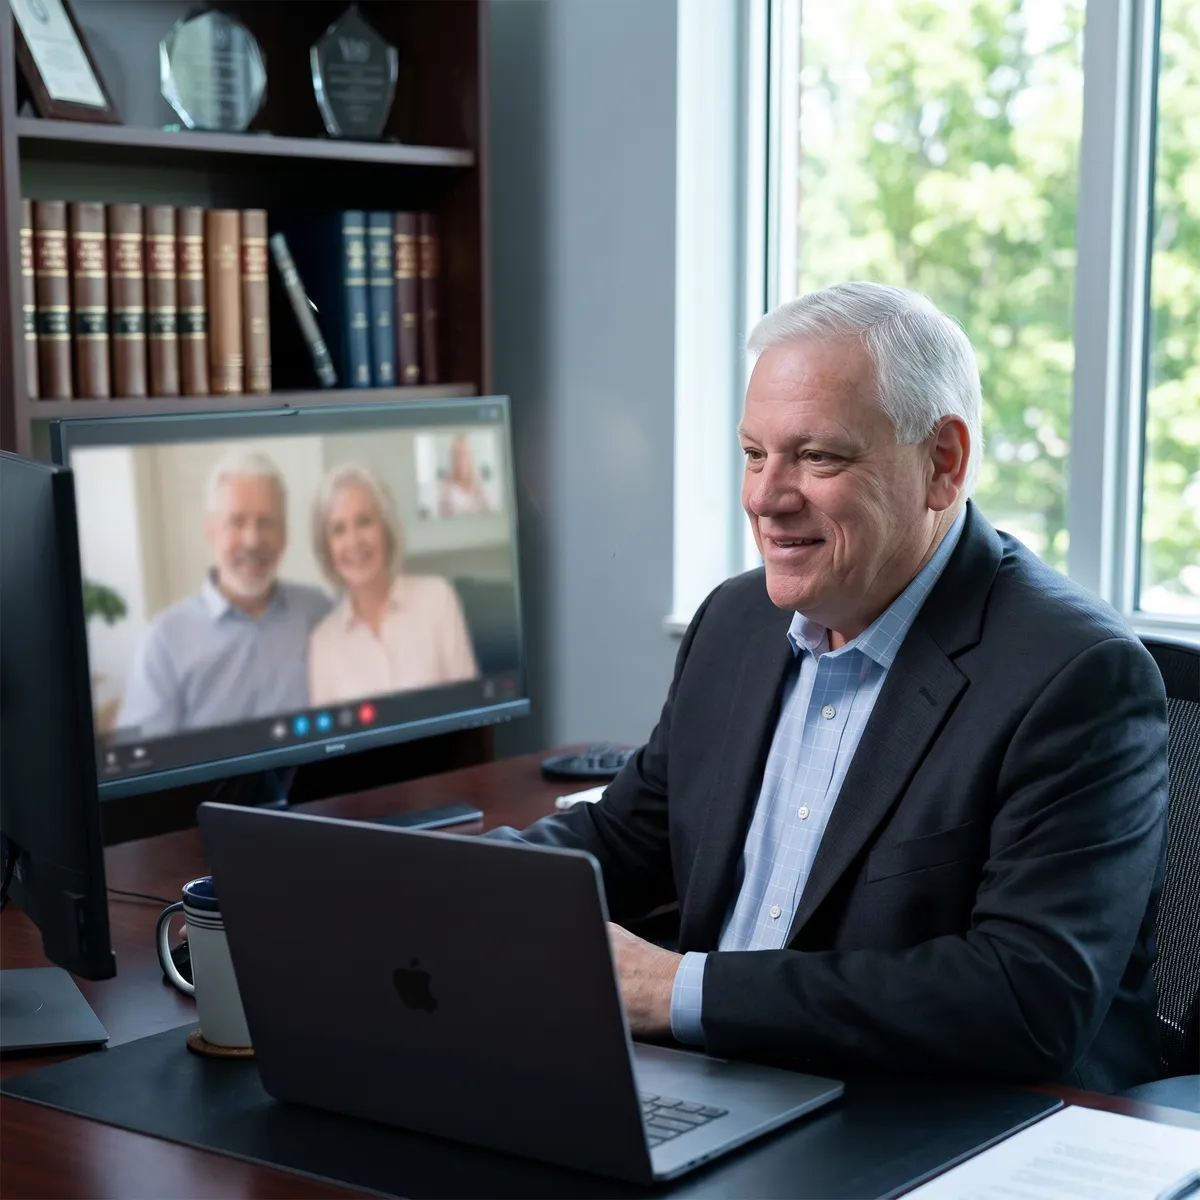
In your complimentary session, Mike Sloan, your Camas Wealth Orchestrator, won't hand you a generic brochure or a one-size-fits-all sales pitch. He'll sit down with you, gather the details that matter, and run the numbers specific to your life.
Because every family's situation is different, your health, your location, your assets, your existing coverage, your obligations — they all shape the plan. And until someone models it out with your actual data, you're making one of the most important financial decisions of your life based on assumptions.
This consultation replaces assumptions with answers.
Camas Advice · Long-Term Care Planning
What's Included in Your Consultation
A comprehensive review — not a sales call.
Income Needs Analysis
A cost projection specific to your location, your preferred type of care, and realistic inflation — so you know exactly what you're planning for.
Existing Plan Review
If you have current policies or funding strategies in place, Mike will review them and identify what's working, what's outdated, and what's missing.
Risk Assessment
An honest look at where your current plan — or lack of one — leaves you exposed, and where the biggest opportunities for improvement are.
Side-by-Side Options
A comparison of every available strategy — from traditional coverage to modern hybrid solutions — with real numbers, not hypotheticals.
INACTION COST ANALYSIS
A clear picture of what doing nothing actually costs — the tax drag of self-paying and the compounding exposure for every year you wait.
Legal & Estate Checklist
A checklist of the critical legal and estate planning documents you should have in order, regardless of which direction you choose.
Your Camas Wealth Orchestrator
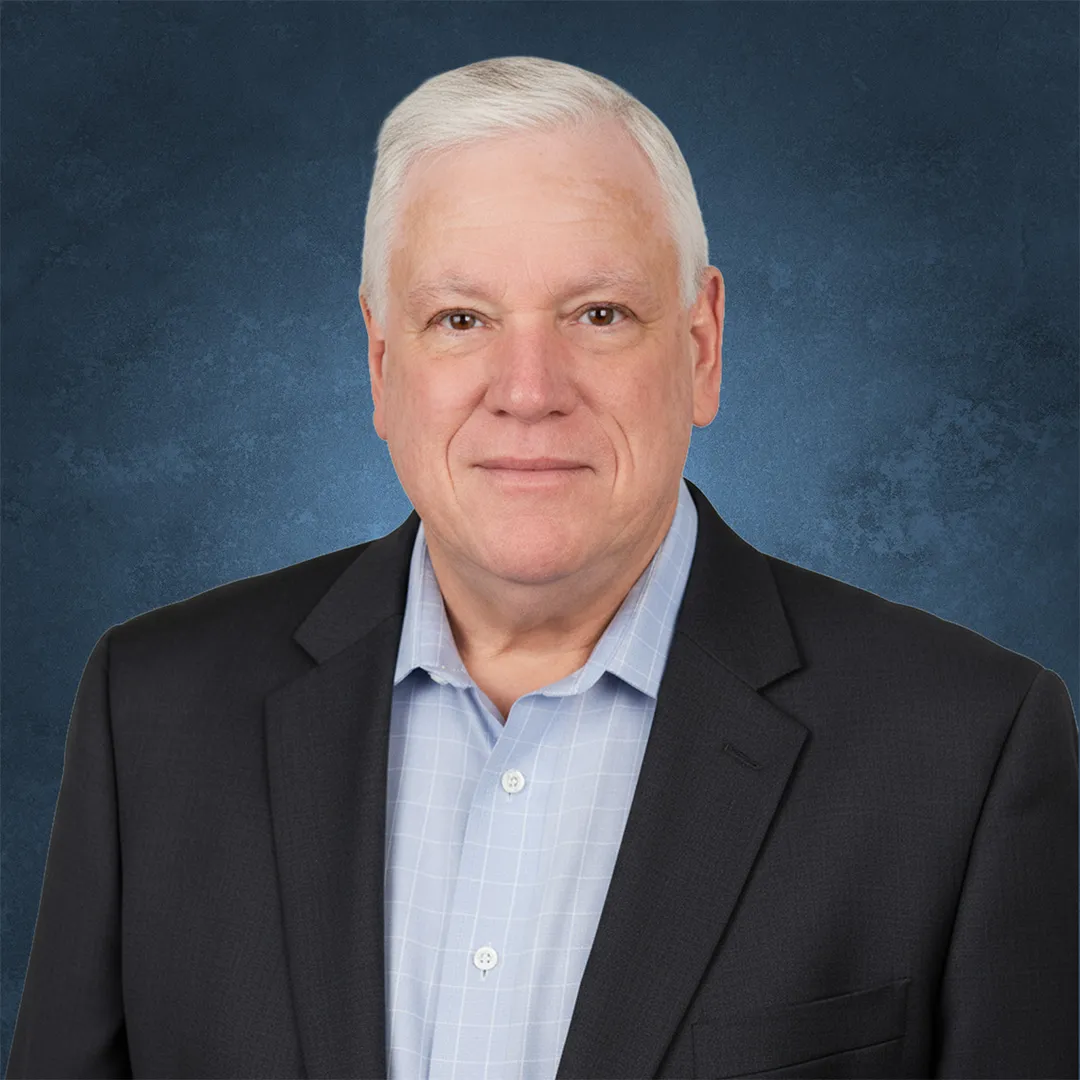
Mike Sloan, CRPC®
Camas Advice · WEALTH ORCHESTRATOR
With over 30 years of experience as a Chartered Retirement Planning Counselor® and Investment Advisor Representative, Mike specializes in one of the most overlooked risks in retirement planning: the financial and personal consequences of extended care. His approach is research-driven — not opinion-driven — built on a detailed analysis of your specific situation, your costs, and your options.
As a Camas Wealth Orchestrator, Mike works alongside a national team of specialists in advanced tax planning, retirement income strategies, and estate coordination to ensure your extended care plan doesn't exist in isolation — it works in concert with every other financial decision you've made. His role is to run the numbers, lay out the options side by side, and give you the clarity to make a confident decision on your timeline.
Mike is based in Clermont, Florida and serves clients across the United States. When he's not helping families plan for what's ahead, you'll find him on a trail with his camera, on the water with a fishing rod, or searching Florida's beaches for Spanish treasure.
This work is personal for me...
"My father was diagnosed with Alzheimer's, and I watched what that does to a family — the daily toll of caregiving, the fear of what comes next, the decisions no one feels ready to make. Thankfully, my parents had followed my advice and purchased a long-term care policy. When my dad needed full-time care in an assisted living facility for the last two years of his life, that policy covered every dollar. When he passed away, my mom kept her home, kept her savings, and lived the rest of her life with the financial security he wanted her to have. Not every family gets that outcome. I've made it my life's work to make sure yours does."
"We had been putting off this conversation for years. Mike sat down with us, ran the numbers specific to our situation, and for the first time we actually understood what our options were. No pressure, no sales pitch — just clarity. We walked away with a plan and the peace of mind that our kids won't be burdened with this down the road."
"I was convinced I couldn't get coverage because of my health history. Mike showed me options I didn't know existed. He was honest about what would and wouldn't work, and he never tried to push me into something that wasn't a good fit. I wish I had done this ten years ago — but I'm grateful I did it now."
"Our financial advisor referred us to Mike, and it was one of the best introductions he ever made. Mike worked with our existing team to build an extended care plan that fit into everything we'd already set up — our estate plan, our tax strategy, all of it. The whole process was painless and we finally feel like we have this covered."
Camas Advice · Long-Term Care Planning
How It Works...
A straightforward process designed around clarity — not pressure.
.01
SCHEDULE YOUR CALL
Pick a time that works for you. The meeting is virtual, private, and at no cost.
.02
SHARE YOUR DETAILS
Complete a questionnaire so we can prepare an analysis specific to your life.
.03
WE RUN YOUR NUMBERS
Real scenarios using your data, what care costs in your area and where the gaps are.
.04
YOU SEE EVERY OPTION
Costs, benefits, and trade-offs, side by side so you can decide with confidence.
The People You Love Are Counting on a Plan... Even If They'd Never Ask for One.
Your children won't bring this up at dinner. Your spouse might mention it once or twice and then let it go. The people closest to you won't push — because they respect your independence, your judgment, your strength.
But if the day comes when care is needed and there's no plan in place, they're the ones who carry the weight. They make the phone calls. They navigate the system. They reorganize their lives. They make impossible financial decisions under impossible emotional pressure. And the relationships between siblings — the ones who help and the ones who don't — may never fully recover.
A good plan addresses both sets of consequences — the financial and the personal. It preserves your retirement, your estate, and the promises you've made. And it allows your family to supervise your care rather than provide it.
You will never be younger than you are today. The options available to you now — the pricing, the coverage, the strategies — will only narrow with time.
Still Have Questions? We Have Answers.
The most common questions we hear from people in exactly your position — answered honestly.
Q: What if I already have a financial advisor?
A: Mike works alongside your existing team — your CPA, your attorney, your financial advisor — not instead of them. Extended care planning is a specialty that complements the work they've already done. In fact, many of our consultations are referred by those same professionals because they want a specialist coordinating this piece of their client's plan.
Q: I'm already in my 70s. Is it too late to plan?
A: No. Mike has designed extended care plans for individuals from their late 40s to their early 80s. Your options may look different than someone in their 50s, but they exist — and some of the most creative and effective strategies are specifically designed for people in your stage of life. The only way to know what's available to you is to run the numbers.
Q: What if I have health issues? Can I still get coverage?
A: Many people assume a health condition automatically disqualifies them and never even explore their options. That's a mistake. As an independent advisor, Mike has access to every carrier in the market, and each one underwrites differently. Conditions that are an automatic decline with one company may be perfectly acceptable with another. The consultation will tell you exactly where you stand.
Q: Is this really free? What's the catch?
A: The consultation is complimentary because the best plans start with understanding your specific situation — and that takes a real conversation, not a generic brochure. Mike will run your numbers, show you your options, and answer your questions. There is no obligation to purchase anything. If you decide this isn't for you after the call, that's completely fine.
Q: How long does the consultation take?
A: About 30 minutes. It's conducted virtually, so you can do it from home on a schedule that works for you. Before the meeting, you'll complete a brief questionnaire so Mike can prepare an analysis specific to your situation rather than walking you through a generic script.
Q: What happens after the consultation?
A: Mike presents your options — costs, benefits, trade-offs — laid out side by side. You decide on your own timeline. There are no high-pressure follow-ups, no "limited time" deadlines, no callbacks unless you ask for them. The goal is clarity, not a close.
Take the First Step — Book Your Complimentary Consultation
Choose a time that works for you. When booking, you can add your spouse, a family member, a trusted friend, or your financial advisor — anyone you'd like by your side for the conversation. You'll receive a confirmation email with everything you need to prepare.
Your information is private and will only be used to schedule your consultation. No spam. No sharing. No obligation whatsoever — if you decide this isn't for you after the complimentary consultation, that's completely fine.
Investment Advisory services offered through: Financial Management Services of America, an SEC Registered Investment Advisor
© 2026 Camas Advice, LLC. All rights reserved. · Orchestrating Wealth.
DISCLOSURES: Camas Advice, LLC is not a law firm or CPA firm. This consultation does not constitute legal, tax, or investment advice. Insurance products are offered through properly licensed professionals. Individual results, costs, and coverage will vary based on personal circumstances, health status, and state of residence. Consult your own tax and legal advisors before making financial decisions.
DISCLAIMER:
This site is not a part of the Facebook website or Meta Platforms, Inc., Instagram or Meta Platforms, Inc., YouTube or Google LLC, TikTok or ByteDance Ltd., Twitter (now known as X) or X Corp., or LinkedIn or LinkedIn Corporation. Additionally, this site is NOT endorsed by Facebook, Instagram, YouTube, Google, TikTok, Twitter (X), or LinkedIn in any way.
TRADEMARKS:
· "ORCHESTRATING WEALTH", "CAMAS WEALTH ORCHESTRATOR", and "D.A.R.E.™ Review Method from Camas Advice" are trademarks of CAMAS ADVICE, LLC.
· FACEBOOK and INSTAGRAM are trademarks of META PLATFORMS, INC.
· YOUTUBE and GOOGLE are trademarks of GOOGLE LLC.
· TIKTOK is a trademark of BYTEDANCE LTD.
· TWITTER and X are trademarks of X CORP.
· LINKEDIN is a trademark of LINKEDIN CORPORATION
RESULTS DISCLAIMER:
The savings, returns, and outcomes mentioned on this site are individual results and are not guaranteed. These examples are provided for illustrative purposes only and may not reflect the typical user's experience. Your results may vary and depend on a variety of factors, including but not limited to your financial situation, market conditions, the information you provide, and the effort you put forth.
We do not guarantee any specific outcomes, and past performance does not indicate future results. All financial activities involve risk, and you could lose money. You should consult with a qualified financial advisor before making any investment or financial decisions. If you're not willing to accept this risk, please DO NOT USE OUR PRODUCTS OR SERVICES.